
CAG’s Power-Sector Audit: DISCOM Accountability, Investment and Consumer Service
Revise the static topic: UPSC Polity notes · UPSC Governance notes
In short: The Comptroller and Auditor General of India is undertaking a comprehensive power-sector audit, beginning with 39 DISCOMs and five departmental undertakings, with privately owned DISCOMs excluded from this exercise. Its focus on consumer experience, power procurement and financial sustainability can connect public expenditure scrutiny with service delivery and strengthen accountability for power-sector reforms.
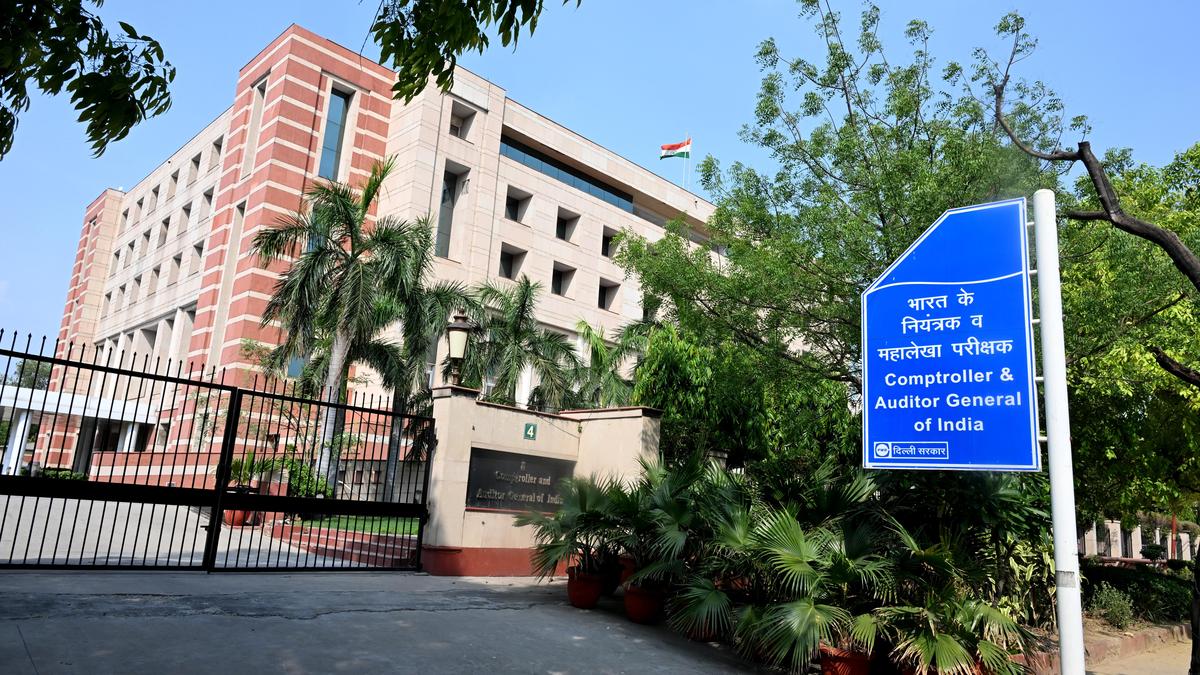
Photo from the source report: CAG’s Power-Sector Audit: DISCOM Accountability, Investment and Consumer Service
Image: The Hindu
Why in news
The reported audit moves beyond financial and operational indicators to include direct engagement with around 10,000 electricity consumers. Subsequent coverage is planned for transmission, generation, renewable energy and the Revamped Distribution Sector Scheme.
39
DISCOMs covered
5
Departmental undertakings covered
Around 10,000
Consumers to be engaged
Nearly 14%
Reported short-term procurement share
More than 56%
Exchange share of short-term transactions
₹3 lakh crore
Projected Central investment, per TOI headline
Background
Electricity distribution is the consumer-facing link in a chain comprising generation, transmission and distribution. DISCOMs procure electricity, supply it to consumers, bill consumption and collect revenue; weaknesses in their finances can affect payments throughout the sector. Electricity falls in the Concurrent List, while the Electricity Act, 2003 provides the principal statutory framework for sectoral regulation. The CAG is a constitutional authority under Article 148, with duties and powers prescribed under Article 149 and parliamentary law. Performance auditing examines economy, efficiency and effectiveness, complementing scrutiny of financial reporting and compliance.
What the audit covers—and what remains uncertain
According to The Hindu, the initial phase covers 39 DISCOMs and five departmental undertakings. Privately owned DISCOMs are outside this exercise. Transmission, generation, renewable energy and RDSS are to be examined subsequently, while engagement with the coal department is intended to support an integrated sectoral assessment.
Officials describe a five-year assessment, but the report also identifies the DISCOM coverage as FY21–FY26. These descriptions do not align neatly as an inclusive financial-year range; the precise coverage should therefore be checked against the official audit terms rather than inferred.
The Times of India headline links the exercise to safeguarding projected Central investment of ₹3 lakh crore. The supplied extract does not establish the investment’s components, approval status or disbursement schedule; it should not be treated as an independently verified RDSS allocation.
- The reported widening concerns the audit programme’s coverage, not an announced enlargement of the CAG’s constitutional powers.
- Findings are to reach respective state legislatures through State Audit Reports.
- Common systemic concerns are subsequently to be consolidated for the Union Ministry of Power’s consideration.
Infographic
Investment
Test whether expenditure produces functioning assets.
Procurement
Examine purchase planning, costs and risk management.
Utility finances
Assess losses, billing, collection and viability.
Consumer service
Verify supply reliability and quality through evidence.
Accountability
Connect audit findings with legislative scrutiny and corrective action.
AI-assisted infographic by Pragnya IAS Academy, based on the cited sources.
From expenditure checking to consumer-centred performance audit
The CAG has asked auditors to engage directly with electricity consumers, alongside local experts and other groups. The exercise seeks experiences from industrial, agricultural and domestic users, particularly on reliability and quality of supply. This can test whether reported improvements in utility performance translate into actual service gains.
A performance audit can distinguish spending from results: expenditure on distribution infrastructure is an input, functioning infrastructure is an output, and improved supply reliability is an outcome. Consumer testimony is valuable evidence, but should be triangulated with outage records, billing data, complaint registers and field verification.
- Economy asks whether resources are acquired at appropriate cost without compromising required quality.
- Efficiency asks whether resources are converted into services with minimum avoidable waste.
- Effectiveness asks whether investments and reforms achieve their intended objectives.
- Consumer satisfaction should complement, not replace, independently verifiable service indicators.
Why procurement and DISCOM finances matter
The Hindu reports that short-term procurement has risen from around 7–8% of states’ overall power purchase basket five years ago to nearly 14%, with power exchanges accounting for more than 56% of such transactions. Procurement costs influence both utility finances and the costs ultimately borne by consumers, subject to regulatory treatment.
A larger short-term procurement share is not automatically evidence of inefficiency. Such purchases can help meet unexpected demand or supply shortfalls. Auditors should examine whether purchases reflected sound forecasting, competitive processes and prudent risk management, rather than judge decisions solely by prices observed later.
AT&C losses, billing efficiency and collection efficiency connect physical supply to realised revenue. Weak performance can impair payments to generators and transmission entities, constrain maintenance and increase fiscal pressure. Financial sustainability must therefore be assessed alongside service quality, rather than through cost reduction alone.
- Examine whether investment addresses identifiable network and service bottlenecks.
- Distinguish technical losses from metering, billing and collection weaknesses.
- Assess procurement decisions using information available when they were made.
- Test whether financial improvements coexist with reliable and equitable supply.
Constitutional accountability and the limits of audit
Article 148 establishes the CAG’s constitutional office and safeguards its independence. Article 149 enables Parliament to prescribe its duties and powers; the CAG’s Duties, Powers and Conditions of Service Act, 1971 supplies the principal statutory framework. Audit arrangements for government companies also operate within the Companies Act, 2013.
Under Article 151, CAG reports relating to state accounts are submitted to the Governor, who causes them to be laid before the state legislature. Legislative committees, including the Public Accounts Committee and the Committee on Public Undertakings as applicable, provide mechanisms for examining audit findings and seeking executive accountability.
The CAG does not replace electricity regulators, fix tariffs or manage DISCOM operations. Similarly, excluding private DISCOMs from this particular exercise does not establish a universal exemption from every legally permissible audit. The legal basis and scope must be assessed in each case.
- Audit identifies weaknesses; executive agencies must implement corrective measures.
- Regulatory decisions remain within the jurisdiction established by electricity law.
- Sharing systemic findings with the Union Ministry of Power complements, rather than substitutes for, state legislative scrutiny.
| Audit dimension | Core question | Evidence to examine |
|---|---|---|
| Financial and compliance scrutiny | Are financial reporting and transactions consistent with applicable requirements? | Accounts, supporting records, contracts and approvals |
| Procurement performance | Were purchases planned and executed prudently? | Demand forecasts, purchase schedules and contemporaneous market conditions |
| Operational efficiency | Are network and revenue losses being addressed? | Energy accounts, metering records, billing and collection data |
| Consumer outcomes | Has service reliability and quality improved? | Consumer feedback, outage logs and complaint records |
| Investment effectiveness | Does expenditure deliver intended improvements? | Project completion, asset functionality and service outcomes |
- 1. Define audit objectives, criteria and legally authorised coverage.
- 2. Examine expenditure, procurement, operational and financial records.
- 3. Triangulate consumer experiences with service data and field evidence.
- 4. Present state-level findings through the constitutional reporting route.
- 5. Use legislative scrutiny and consolidated systemic findings to identify corrective priorities.
- 6. Track executive action and verify improvements in finances and consumer service.
1971
The CAG’s Duties, Powers and Conditions of Service Act provides the principal statutory framework for its functions.
2003
The Electricity Act establishes the principal contemporary framework for electricity-sector regulation.
July, according to the report
The comprehensive power-sector audit commences, beginning with distribution.
Subsequent audit stages
Coverage is planned to extend to transmission, generation, renewable energy and RDSS.
Significance, challenges & way forward
Significance
- Consumer engagement can reveal service deficiencies that aggregate financial indicators overlook.
- Procurement scrutiny can identify avoidable costs and strengthen accountability for decisions affecting utility finances and consumers.
- Auditing DISCOMs first addresses the revenue-collection link on which the wider electricity value chain depends.
- Examining investment effectiveness can shift attention from expenditure utilisation to functioning assets and measurable outcomes.
- State-level reports and consolidated policy findings can support learning across jurisdictions while preserving legislative accountability.
Challenges
- Differences in consumer mix, geography and network conditions can make unadjusted comparisons between DISCOMs misleading.
- Incomplete metering, inconsistent records and weak outage reporting can undermine the reliability of audit conclusions.
- Consumer engagement requires representative sampling to avoid over-representing vocal or easily accessible groups.
- Procurement assessment risks hindsight bias if auditors overlook contemporaneous demand uncertainty and supply constraints.
- Exclusion of private DISCOMs limits this exercise’s sector-wide coverage, although it does not determine their position under all audit laws.
- Audit recommendations may have limited impact without legislative follow-up, assigned responsibility and verified corrective action.
Way forward
- Clarify the assessment period, selection criteria and scope through authoritative audit documentation.
- Use comparable indicators while accounting for agricultural demand, settlement patterns and network characteristics.
- Combine independently verified service records with representative feedback across consumer categories.
- Assess procurement against contemporaneous information, contractual constraints and risk-management practices.
- Link investment appraisal to asset functionality, loss reduction and consumer outcomes rather than expenditure alone.
- Require time-bound action-taken responses and follow-up verification through appropriate legislative and executive mechanisms.
- Translate recurring findings into coordinated Union–State reforms without diluting state-level accountability.
Key terms
- Performance audit
- An examination of whether public activities or programmes operate with economy, efficiency and effectiveness.
- DISCOM
- An electricity distribution company responsible for supplying electricity to consumers and managing associated billing and collection.
- AT&C losses
- Aggregate technical and commercial losses capture energy losses and revenue shortfalls associated with billing and collection inefficiencies.
- Billing efficiency
- The proportion of input electricity accounted for through billed energy.
- Collection efficiency
- Revenue realised relative to the amount billed over the relevant assessment period.
- Power exchange
- A regulated market platform through which electricity is bought and sold under standardised market arrangements.
- RDSS
- The Revamped Distribution Sector Scheme seeks to improve distribution utilities’ operational efficiency and financial sustainability.
- Action-taken response
- An executive explanation of measures adopted to address audit observations or legislative committee recommendations.
Link with static syllabus
Prelims practice MCQs
Q1. With reference to the Comptroller and Auditor General of India, consider the following statements: 1. Article 148 establishes the constitutional office of the CAG. 2. Article 149 provides for Parliament to prescribe the CAG’s duties and powers. 3. CAG reports relating to state accounts are submitted directly to the Chief Minister for laying before the legislature. Which of the statements given above are correct?
Q2. With reference to performance auditing, consider the following statements: 1. It examines economy, efficiency and effectiveness. 2. Consumer experience can provide evidence about service outcomes. 3. It authorises the auditor to replace the electricity regulator in determining tariffs. Which of the statements given above are correct?
Q3. Consider the following statements about the reported CAG power-sector audit: 1. The initial exercise covers 39 DISCOMs and five departmental undertakings. 2. Privately owned DISCOMs are included in the initial exercise. 3. Common systemic concerns are to be consolidated for consideration by the Union Ministry of Power. Which of the statements given above are correct?
Q4. Which of the following best describes aggregate technical and commercial losses in electricity distribution?
Mains practice questions
GS 2 · 15 marks · 250 words
How can the CAG’s performance audit of electricity distribution strengthen accountability for public investment and consumer service delivery? Discuss the institutional and methodological safeguards required.
Frequently asked questions
Has the CAG received new constitutional powers to audit the power sector?
The supplied reports describe a wider audit programme, not a constitutional amendment or a new grant of powers. The CAG’s authority continues to depend on the Constitution and applicable law.
Why are DISCOMs being audited first?
DISCOMs directly serve consumers and collect revenue for electricity supplied. Their operational and financial weaknesses can affect generators, transmission entities and the wider economy.
Are private DISCOMs covered?
Privately owned DISCOMs are excluded from this reported exercise. That exclusion should not be interpreted as a blanket legal exemption from every possible CAG audit.
Can the audit itself lower electricity tariffs?
The CAG does not set tariffs. Its findings may identify avoidable costs and support corrective action, while tariff decisions remain with the competent electricity regulators.
Sources
- The Hindu: CAG widens purview of power sector audit, starting with DISCOMs; consumer satisfaction in focus
- Times of India: 39 Discoms come under CAG scanner to ringfence projected Central investment of Rs 3 lakh cr
Analysis prepared by the Pragnya IAS Academy current-affairs desk with AI assistance from the cited reports. Verify figures with the original sources.
Turn current affairs into marks
Join Pragnya IAS Academy's mentorship for daily answer-writing evaluation on stories like this — classroom programmes from a trusted name in IAS coaching in Hyderabad.